Senior Life Insurance Exams: Cognitive Questions, Passing Scores, and Physical Tests
Learn what happens during a senior lifeinsurance exam, including word-recall passing scores, clock-drawingrequirements, mobility testing, social activities, cognitive questions, andpreparation tips.
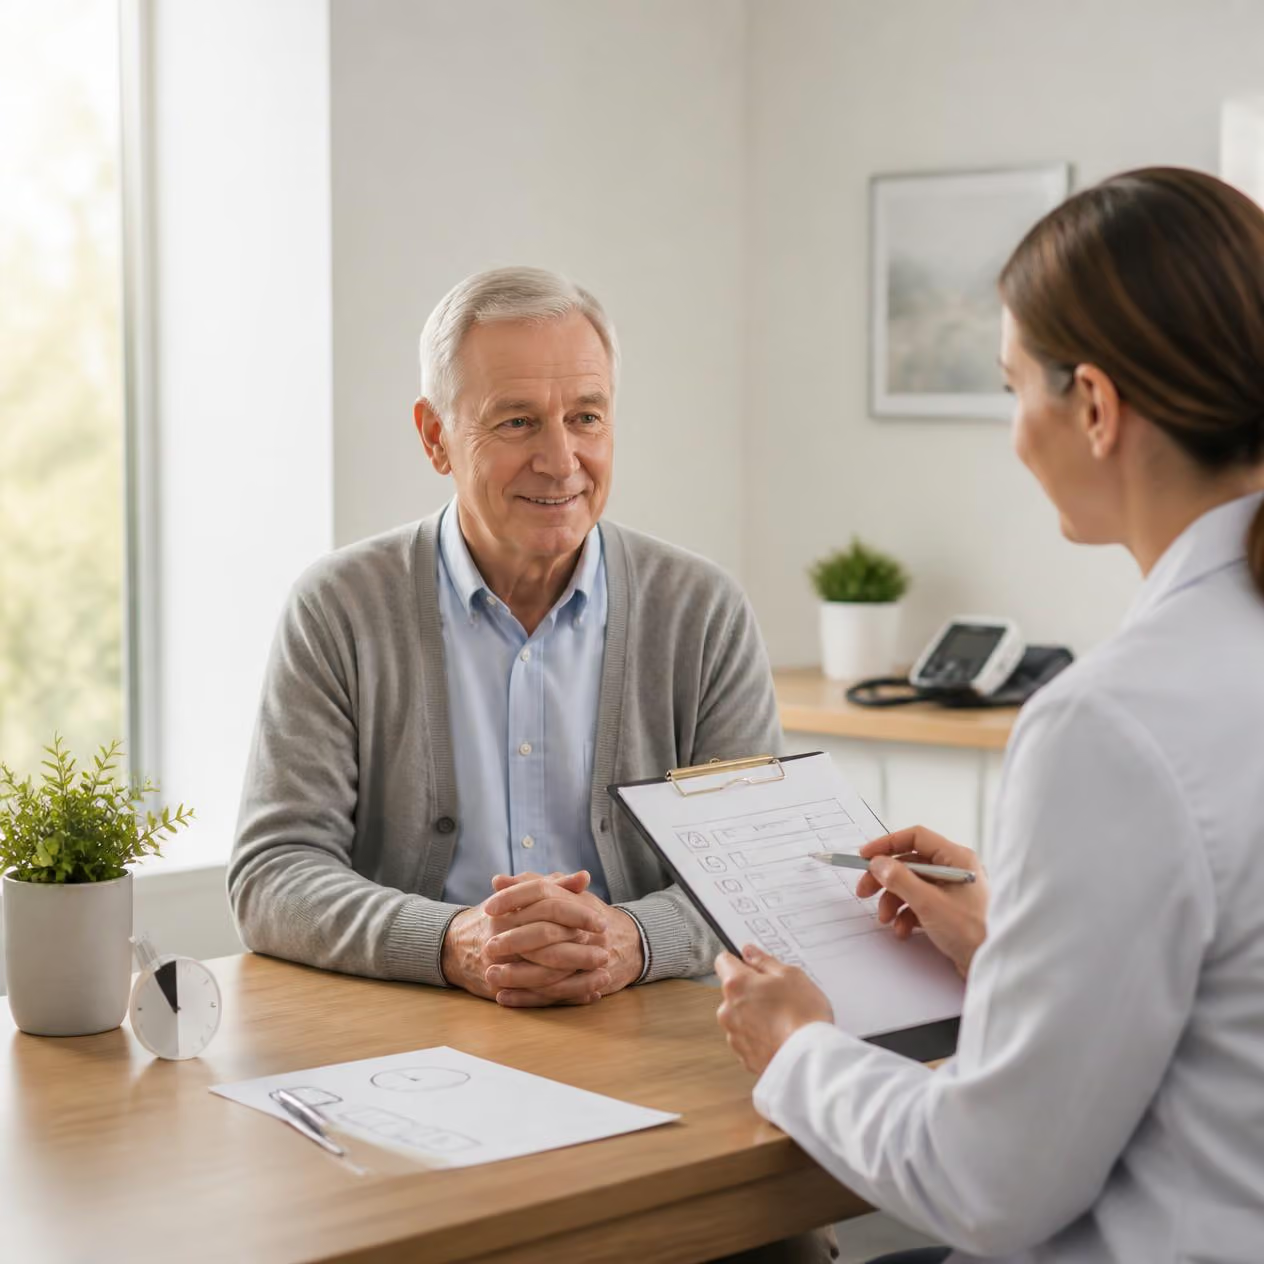
Many life insurance companies require older applicants to complete a senior supplement, cognitive assessment, or functional capacity exam. This additional life insurance underwriting requirement evaluates memory, orientation, mobility, independence, and the ability to perform activities of daily living.
At What Age Is a Senior Exam Required?
Requirements vary by life insurance carrier, product, healthhistory, and policyamount.
Senior assessments commonly begin at age 70 or 71. For example, Symetra requires a senior supplement beginning atage 70, while North American applies additional cognitive and functional underwriting considerations beginning at age 71. Advisors shouldverify the carrier's current age-and-amount requirements before scheduling the life insurance medical exam.
What Questions and Activities Are Included?
A publicly available Sun Life Supplemental Senior Care Assessment provides a useful real-life example. It asks about orientation, daily activities, memory,mobility, and independence.
Common questions and activities include:
• The month, date, day of the week, year, season,current president, and applicant's age
• Driving, exercise, employment, volunteering, travel, social activity, and history of falls
• Assistance with bathing, dressing, eating, toileting, continence, or transferring
• Delayed word recall and drawing a clock showing a requested time
• Standing from a chair, walking 10 feet, turning,returning, and sittingdown
The examiner may also observe whether the applicant understands instructions, uses a cane or walker, or relies on another person for assistance.
How Many Words Must an Applicant Remember?
The delayed word-recall test varies by carrier. Some assessments use three words; others use ten words and request recall after five to ten minutes.In a ten-word insurance test,recalling at least six words is often described as a passing result, but this is not a universal carrier rule. Each insurer may use its own scoring method and may consider the result with the applicant's complete medical andfunctional profile.
The published Mini-Cog uses three words, awarding one point for each word recalled without prompting. The clock drawing receives either zero or two points, producing a five-point total. A score of three tofive indicates a lower likelihood of dementia, although it does not rule outcognitive impairment. Mini-Cog is a screening tool, not a diagnosis or a universal life insurance passing standard.
Memory technique: Connect random practice words through a vivid story. If the words are apple, train, jacket, river, and dog, imagine a dog wearing a jacket and carrying an apple onto a train that crosses a river. Practice the technique rather than memorizing an insurer's actual questionnaire.
What Is Evaluated in the Clock-Drawing Test?
A normal Mini-Cog clock generally includes:
• All numbers from 1 through 12, with each number appearing only once
• Numbers placed in the proper clockwise order and approximately correct positions
• One hand pointing to 11 and another pointing to 2 when the requested time is 11:10 Hand length is not scored under the Mini-Cog method.The task evaluates comprehension, planning, visual-spatial ability,numerical knowledge, working memory, and the ability to follow a multistep instruction. Do not rush. Place 12, 3, 6, and 9 first, add the remaining numbers,listen carefully to the requested time, and then draw the hands.
What Is Evaluated During the Chair-and-Walking Test?
The Timed Up and Go test generally asks the applicant to stand from a chair,walk 10 feet, turn, return, and sit down. Theexaminer may record:
• Total completion time and ability to rise on the first attempt
• Use of the arms, a cane, walker,wall, or anotherperson
• Balance, posture, stridelength, walking speed,body sway, or shuffling
• Stability while turningand the abilityto sit down smoothly
The test helps evaluate leg strength, balance, coordination, fall risk, mobility, frailty, and independent living ability. The CDC notes that taking 12 seconds or longer may indicate increased fall risk, but life insurers may apply their own underwriting standards rather than treating12 seconds as a universal pass-or-fail score.
Why Do Insurers Ask About Travel, Exercise, and Social Activities?
Questions about walking, sports,childcare, travel, book clubs, volunteer work, community service, church activities, hobbies, and helping family or friends are not casual conversation.They help an underwriter understand the applicant's functional age - how independently and actively the person lives - instead of relying only on chronological age and medical records.
• Walking, tennis,golf, swimming, gardening, and exercise classes may demonstrate mobility, balance, coordination,strength, endurance, and consistent physical activity.
• Travel may involve planning,packing, navigating airports, managing schedules and medications, handling money, andadapting to unfamiliar surroundings.
• Caring for grandchildren or providing childcare may demonstrate responsibility, attention, stamina, mobility, and the ability to manage changing situations.
• Book clubs, card groups,music groups, and classes may indicate continued reading, communication, memory, concentration, and social engagement.
• Church, volunteer, charitable, and community activities may show regular participation, transportation independence, organization, communication, and meaningful social connections.
• Helping relatives or friends may demonstrate independence and an abilityto assist others rather than needing assistancewith routine activities.
North American's underwriting guidance for applicants age 71 and older specifically identifies physical activity, travel,exercise, social activities, and independence in activities of daily living as favorable considerations. TheCDC also reports that supportive social connections are associated with better physicaland emotional health,reduced loneliness, greaterquality of life, and longer life.
Do These Activities Have a Point Value?
There is generally no publicly disclosed, universal point system awarding a fixed number ofpoints for taking a trip,attending church, playing tennis, helping with childcare, or belonging to a book club. Unlike the published Mini-Cog scoring system, these lifestyle answers are usually evaluated as partof the applicant's overall underwriting profile.
A carrier may treat sustained physical activity, recent travel, social engagement, and independenceas favorable evidence, particularly when considering a preferred underwriting classification. However, one activity does not guarantee approval or a particular rate class. Frequency,consistency, independence, medical history, cognitive testing, mobility, falls,and the complete application are considered together.
How Should Applicants Prepare?
Schedule the exam when you are rested, alert, hydrated, and not rushed. Eliminate television,telephone, and household distractions. Wear your normal glasses, hearing aids,footwear, and prescribed walking aids. Review the current date, day, month, year, and season.Listen carefully, take every question seriously, and request clarification whenneeded.
Review the Previous 12 Months
Before the senior life insurance exam, make a truthful list of your activities during the past year so that you do not overlookmeaningful parts of your normal life. Include:
• Trips taken, destinations, approximate dates, duration,and purpose
• Walking, exercise, tennis, golf, swimming,gardening, or other sports
• Childcare or assistance provided to familymembers
• Church attendance, committees, and faith-based activities
• Volunteer work, community involvement, clubs, classes,hobbies, and socialgatherings
• Household responsibilities, shopping, driving, medication management, and financial management
Applicants sometimes answer 'not much' because they are surprised and cannot immediately remember everything they do. Reviewing the year helps the applicant give a complete, accurate description. Activities should never be exaggerated or invented.
If the examiner speaks too quickly, the telephone connection is poor, or an accent makes instructions difficult to understand, politely ask for repetition. If communication remains unclear - or you are sick, unusually tired, or rushed - request another appointment. Health, fall-history, mobility, and daily-activity questions should always be answered completely and truthfully. Preparation should help applicants present their actual abilities accurately, not conceal cognitive or physical limitations.
Lifeinsuranceopedia Original Practice Senior Assessment
Page 1 of 2 - Practice Questions
Important notice: This sample assessment was created for Lifeinsuranceopedia as an educational practice tool for people preparing for the senior portion of a life insurance medical examination. It is not an official insurance-company examination, a medical diagnosis, or a copy of any carrier's proprietary or copyrighted test. Providing an insurer's exact examination or copying protected testing material would be inappropriate.
The purpose is not to memorize answers or conceal a limitation. Most people have never been asked to remember unrelated words,draw a clock on command,identify the exact date, or walk while being timed. Familiarity may keep an otherwise capable applicant from becoming flustered, rushed, or experiencing stage fright when these unusualrequests are made.
Instructions for the Practice Examiner
Ask a family member, friend, or advisor to administer the assessment. The applicant should not study the questions or wordlist in advance.Read each instruction slowly and clearly.Do not give hints unless the instructions allowthem.
Record what happens without criticizing, coaching,or interrupting.
1. Orientation Questions - 7 Practice Points
Award one practice point for each accurate response.
• What is today's month?
• Whatday of the week is it?
• Whatis today's date?
• Whatyear is it?
• What season is it?
• Whois the current president of the UnitedStates?
• How old are you? Orientation score________ outof 7
2. Original Word-Registration Exercise
Read these original practicewords slowly. Ask the applicantto repeat them once and remember them for later.Do not say when they will berequested again.
Lantern - Orange - Bicycle - Ocean - Pillow - Guitar - Window - Rabbit - Market - Silver
3. Everyday Independence and Activities
Answer truthfully and provide detailswhere appropriate.
• Do you drive, shop, preparemeals, manage medications, and pay bills?
• Where have you traveledduring the previous12 months?
• Doyou walk, garden,exercise, play sports,swim, or attendan exercise class?
• Doyou care for grandchildren or help familymembers or friends?
• Doyou attend church,volunteer, or participate in community activities?
• Doyou belong to a book club, card group, socialclub, class, or hobby group?
• Haveyou fallen duringthe past two years?
• Doyou need help bathing, dressing,eating, toileting, walking,or rising from a chair?
These questions have no universalpublished point value. Insurers may consider frequency, consistency, complexity, and independence. Activities must never beexaggerated or invented.
4. Concentration Exercise - 5 Practice Points
Begin with 20 and subtract three five times: 20 -> -> -> -> ->
Award one practice point for each correct number. Score_____ out of 5
Lifeinsuranceopedia Original Practice Senior Assessment
Page 2 of 2 - Drawing,Mobility, and Recall
5. Original Clock-Drawing Exercise - 2 Practice Points
On blank paper, draw a round analog clock. Place all the numbers where they belong and draw the hands to show twentyminutes after eight.
• One point: all numbers 1 through 12 appear once, clockwise, in generally appropriate positions.
• Onepoint: two hands are presentand show approximately 8:20.
Clock score: _____ out of 2 This original scoring method is for familiarization only. It isnot medically validated or carrier approved.
6. Chair, Walking,and Turning Exercise
Safety first: Perform this only with another adult present. Wear normal footwear and use your regularly prescribed cane or walker. Do not attempt it if standing or walking would be unsafe.
Sit in a stable chair.When the examinersays begin, stand,walk approximately 10 feet at your normalpace, turn, walk back, and sit down. Completion time: _____ seconds
• Did the applicant stand on the first attempt?
• Were the arms, a wall, anotherperson, a cane, or a walker used?
• Was the pace steady,with normal stepsand balance?
• Was the turn controlled, and did the applicant sit smoothly?
This exercise may show leg strength, balance,coordination, fall risk,mobility, and independence. There is no universallife insurance passing time.
7. Delayed Word Recall - 10 PracticePoints
Without looking back, name as many words from Section2 as possible. Award one practice point for each correct word.
1. ________ 2. ________ 3. ________4. ________ 5. ________ 6. ________ 7.________ 8. ________ 9. ________ 10. ________
Word-recall score________ out of 10
Some insurance assessments use three words and others may use ten. Carrierscoring varies, so this originalpractice assessment does not establish a passing score.
Helpful Memory Technique
Create one exaggerated mental story connecting the words. Imaginea rabbit riding a bicyclebeside the ocean, carryingan orange and a silverlantern. It stopsat a market, sees a guitar througha window, and falls asleepon a pillow. Practicethis technique with changing random words rather than memorizing one list.
Preparation Checklist
• Review the current day, date, month, year, and season.
• List trips, exercise, sports, childcare, church,volunteer, club, and community activities from the past year.
• Schedule the exam when rested, alert, hydrated, and not rushed.
• Wear normal glasses and hearing aids,and eliminate distractions.
• Ask for repetition if instructions, an accent, or a telephone connection are unclear.
• Request another appointment if illness, exhaustion, or communication problems prevent a fair assessment.
Understanding the practice results: These points only build familiarity with the format. They do not predict approval, determine a life insurance rate, or diagnose cognitive impairment. Preparation should help applicants communicate their genuine abilities accurately, never conceal a limitation.
Sources and Further Reading
Symetra Individual Life Underwriting Requirements andPreferred Guidelines
North American Life Underwriting Guidelines
Sun Life Supplemental Senior Care Assessment
CDC Timed Up and Go Assessment
CDC Information for Older Adults
Pinney Insurance: Senior Supplement and Cognitive Testing
This article is educational and does not establish any carrier's current underwriting requirements or guarantee a particular underwriting decision. Requirements and scoring methods can change and may vary by product, age, policy amount, and applicant history.